
Energy: OPEC Faces Hard Supply Decision in 2025
Our preferred stocks in the energy sector include Exxon and Schlumberger.

Weak global demand has caused yet another delay in unwinding OPEC’s production cuts. Instead of taking place over 2025, the cartel is telegraphing a much longer period, from April 2025 through 2026. This addresses the core problem with OPEC’s prior strategy. Markets didn’t believe a quick rebound in global economic activity would allow for a rapid unwinding, and intense skepticism swirled around each expiration date.
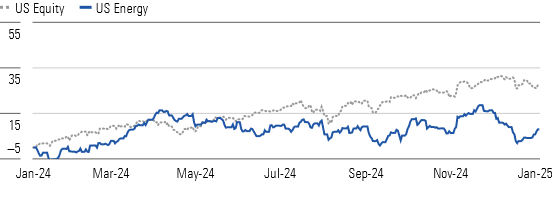
Oil Oversupply Leads to Energy Lagging the Broader Market
By unwinding more slowly, much smaller supply growth reduces the impact on price. Even so, forecasters see non-OPEC supply growth exceeding global demand growth in 2025. Economic activity would have to accelerate, perhaps from greater stimulus in China, to allow OPEC to add back barrels without driving Brent lower. There are substantial reasons to doubt this. Potential tariffs and sanctions would hit the global economy hard and slow activity. This is likely why the cuts aren’t set to unwind until the end of President-elect Donald Trump’s first 100 days. So we’re uncertain whether OPEC will turn the taps back on in April.
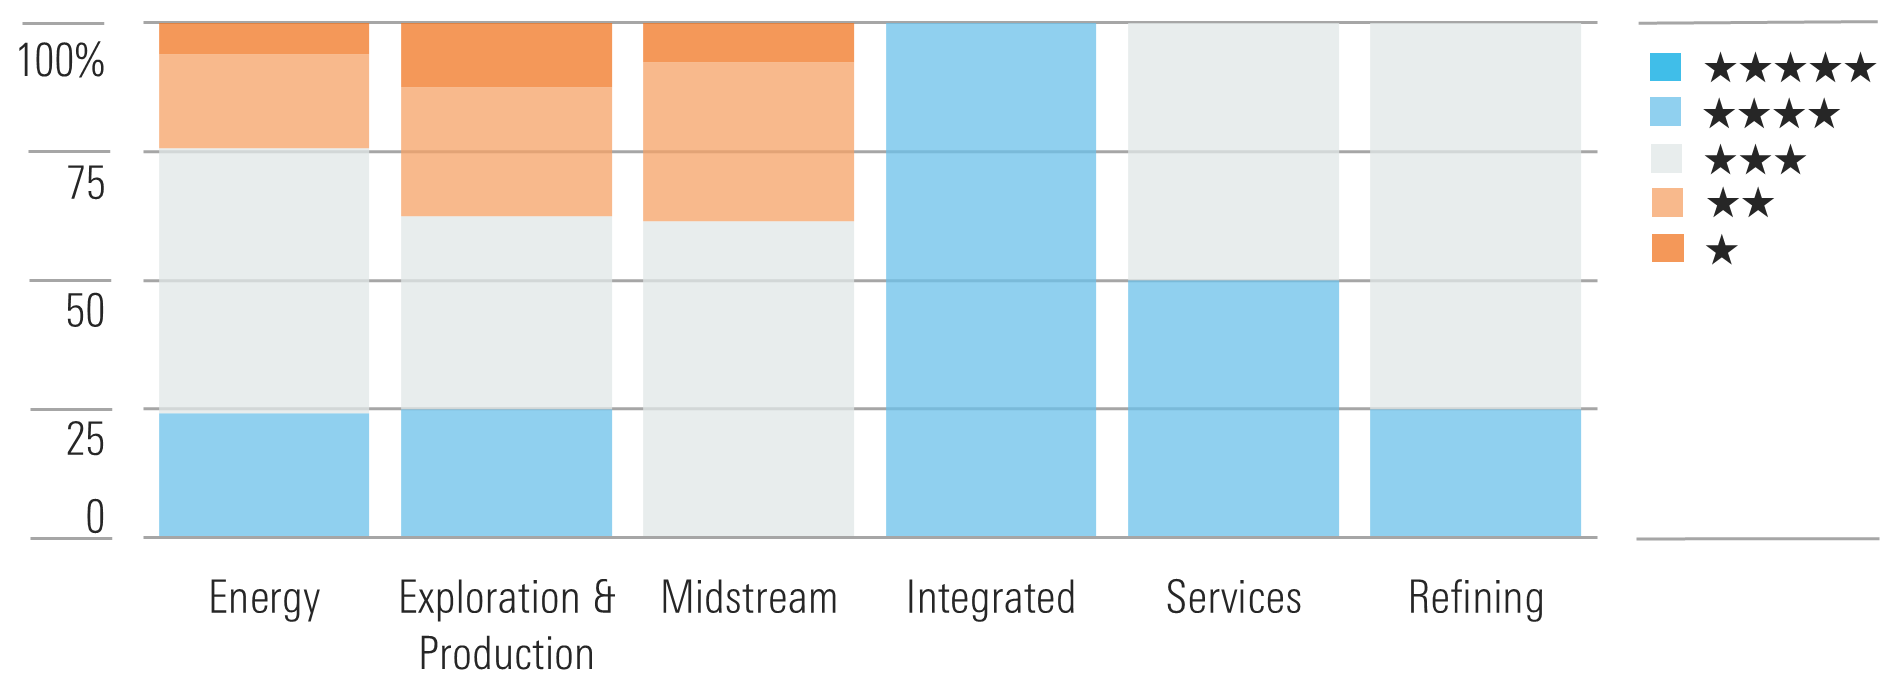
Services Tops Our List of Most Discounted Stocks
Still, we didn’t expect the OPEC we’re seeing on display. This new plan communicates patience and a group willing to see a vision unfold over years rather than months. This type of plan requires substantial commitment from its members and stands in sharp relief to a group that went to war with Russia five years ago to seize market share.
Oil Rig Activity to Remain Lower for Longer Because of Production Efficiencies
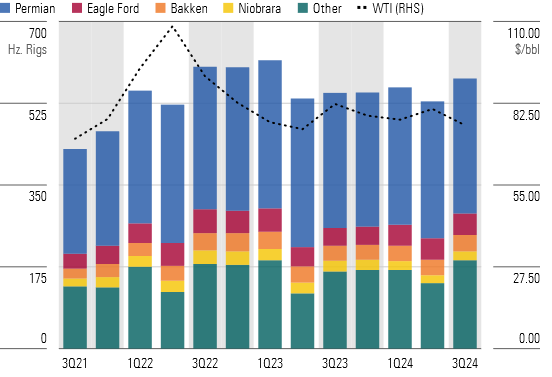
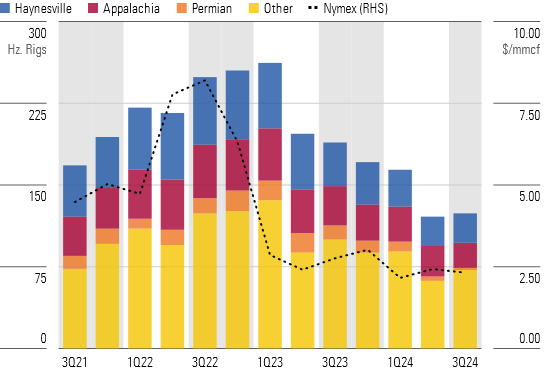
Consolidation and productivity in the Permian drove a slight sequential decline in rig activity. While there was a slight uptick in total production from the third quarter, we don’t see any catalysts to drive activity in the near term. Oil markets remain well supplied, with concerns about oversupply continuing to weigh on prices as geopolitical risks fade. US gas producers remain challenged in the closing months of 2024. However, we think the outlook for this resource is improving. Gas’ improved outlook doesn’t mean more drilling activity, though. Instead, we expect US gas producers to focus initially on previously shut-in wells or deferred wells for near-term production gains at minimal cost before adding rigs.
After Challenging First Half, Gas Producers Have Better Near-Term Outlook
Top Energy Sector Picks
HF Sinclair
- Fair Value Estimate: $58.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: Narrow
- Morningstar Uncertainty Rating: Very High
Sinclair DINO is the lone refiner trading below our fair value estimate. After acquiring Sinclair Oil, HollyFrontier, now Sinclair, is a fully integrated independent company that comprises refining, marketing, renewables, specialty lubricants, and midstream businesses. We expect a new management team to focus on improving operations and rewarding shareholders. Still primarily a refiner, it should benefit from strong market conditions, which should result in higher payouts given management’s plans to pay out 50% of earnings to shareholders. In fact, the firm announced a new $1 billion repurchase program in May.
Schlumberger
- Fair Value Estimate: $57.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: Narrow
- Morningstar Uncertainty Rating: Medium
Schlumberger SLB is among the cheapest stocks in our global energy coverage with a moat. Its multiple trades are in line with peer services firms, but it deserves a premium, given its scale, suite of solutions, competitive position in some of the more attractive services markets, and technological advantage. These factors position the firm to outperform its peers. The company’s offshore segment outside North America boasts a growing project opportunity set that could exceed $100 billion annually over the medium term. Schlumberger’s digital-related revenue is also highly accretive and more resilient to cyclical headwinds. We expect digital revenue can more than double by the end of 2025 to $3 billion and possibly climb to $4 billion by the end of the decade.
ExxonMobil
- Fair Value Estimate: $135.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: Narrow
- Morningstar Uncertainty Rating: High
Exxon XOM plans to double earnings and cash flow from 2019 levels by 2027, on a combination of structural operating cost reductions, portfolio improvement, and growth across its upstream, downstream, and chemical segments. Exxon estimates that under the current plan, it will generate about $100 billion in surplus cash (after funding investments and paying its dividends) during the next five years. Combined with higher-than-expected commodity prices, its current annual repurchase program is $20 billion following its acquisition of Pioneer Resources.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States