
Financial Services: Opportunities in Asset Management and Credit Services
Our favorite stocks in this sector include Ally and Broadridge.

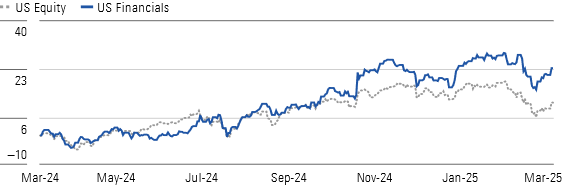
The financial services sector has outperformed Morningstar’s US markets Index by 12 percentage points over the past year, with nearly half of that outperformance coming in the first quarter of 2025. This has been driven by expectations for a lighter regulatory touch and for more permissive antitrust regulation, while strong market returns and higher long-term interest rates over the past couple of quarters are generally positive for the sector.
Expectations for Improving Regulatory Backdrop Have Driven Outperformance
A few cracks have emerged in those theses, particularly with early phases suggesting the FTC’s posture toward mergers and acquisitions will be similar to how it was during the prior administration, while the interest rate curve remains stubbornly flat. Elsewhere, substantial unresolved uncertainty regarding global growth and foreign trade policy has stymied deal flow, to the detriment of firms with large investment banking arms. However, for many companies, this has been offset by strong trading segment results amid market volatility.
While Insurers Look Expensive, Most Financial Sector Industries Are Fairly Priced

Looking ahead, we view risks and opportunities as roughly balanced, with the median financial services firm trading at or around our fair value estimates in most industries. We see the most opportunity in consumer credit services, where delinquencies should prove manageable if our forecasts for slowing but resilient economic growth and OK employment prospects play out. Meanwhile, insurance looks largely overvalued, as the market appears to be contemplating more favorable underwriting conditions and higher pricing over the long term than we view as realistic. The insurance market is highly competitive and generally mean-reverting.
US Yield Curve Remains Unusually Flat, but Prospects Are Improving
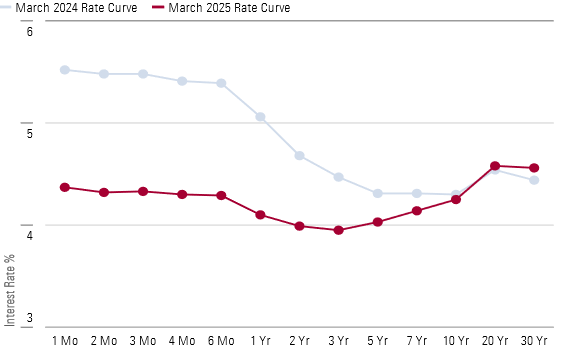
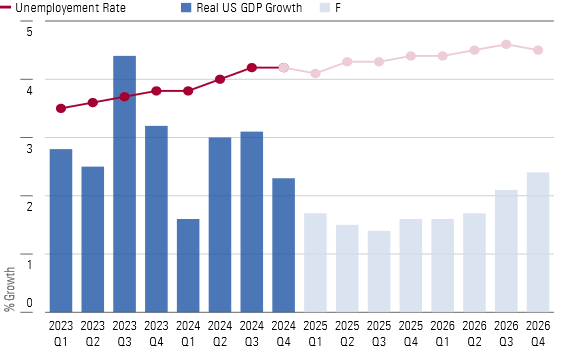
Overall, we view sector prospects as neutral. On one hand, the short end of the interest rate curve should continue to decline, with the Federal Reserve still expecting to cut its base rate twice in 2025. This should drive a steeper yield curve, which is positive for banks, which borrow short and lend long. Less constructively, we’ve seen loan growth slow to an anemic 2.2% during the most recent quarter, according to the FDIC, with significant near-term improvement unlikely given our forecast for slowing real GDP growth and stubbornly high long-term rates.
Expected US Slowdown Looks Manageable
Global Payments
- Fair Value Estimate: $161.00
- Morningstar Rating: ★★★★★
- Morningstar Economic Moat Rating: Narrow
- Morningstar Uncertainty Rating: Medium
While the market is dour on established payment companies like narrow-moat Global Payments GPN, we believe that those firms should be able to navigate the current environment better than market prices suggest, defended by a scale-based cost advantage and switching costs for customers already integrated into their platforms. We forecast mid-single-digit topline growth over the midterm, with margins expanding to nearly 30% by 2029 from 20% in 2024, attributable to fixed cost leverage, a cost reduction program, and a drop in noncash amortization expense. However, we would caution that Global Payments’ reliance on small merchants leaves the company relatively exposed to any near-term shift in the macroeconomic environment.
Ally Financial
- Fair Value Estimate: $48.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: None
- Morningstar Uncertainty Rating: High
While recent pressure for no-moat Ally Financial ALLY has been acute, we believe the market may not fully appreciate the long-term benefits of its mix shift toward its higher-return auto lending business, nor the full benefit of auto loan portfolio repricing on net interest margin expansion. While a sluggish auto market and higher credit costs have weighed on the company’s results, stabilizing used car prices and tighter underwriting are good signs. We expect mid-single-digit net interest income growth over the medium term and roughly 50 basis points of NIM expansion between 2024 and 2029.
Broadridge Financial Solutions
- Fair Value Estimate: $275.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: Wide
- Morningstar Uncertainty Rating: Low
We believe that the market underestimates wide-moat Broadridge Financial Solutions’ BF potential for strong position growth over the medium term, driven by the rise in direct indexing and ongoing strength in managed accounts. Given the outsize contribution of the regulatory business to firm-level profitability, our forecasts leave us modestly but meaningfully ahead of the market consensus for both revenue and adjusted EPS. Taken in tandem with the firm’s Low Uncertainty Rating and improving earnings quality, Broadridge looks attractive at current prices.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States