
Industrials: A Few More Undervalued Stocks After Q4 Underperformance
Caterpillar and Huntington Ingalls are some of our favored industrial picks.

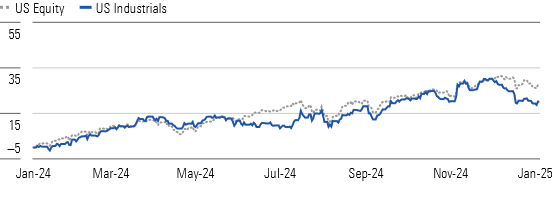
The Morningstar US Industrials Index’s year-to-date performance was in line with that of the Morningstar US Market Index through October. However, notable underperformance from industrial distribution, aerospace and defense, and construction stocks contributed to the sector’s lag relative to the US equity market over the last two months of 2024.
Industrials Index Lost Steam as 2024 Drew to a Close
We believe high valuations and slowing near-term growth prospects for industrial distributors caused investors to take profits in the space. We expect low-single-digit revenue growth on average for Morningstar-covered industrial distributors this year, down from 5% last year and low-double-digit growth in 2021-22.
Stocks with defense exposure, such as L3 Harris, Lockheed Martin, and General Dynamics, have sold off since the US presidential election, as investors fear the industry will be a target of the Trump administration’s announced “Department of Government Efficiency.” But we haven’t altered our forecasts or uncertainty ratings in the US defense sector, because we aren’t convinced the savings would move the $6.8 trillion budget needle, or that DOGE’s efforts would disrupt the businesses of the defense contractors we cover any more than they already have been.
Industrials Sector Still Overvalued, but We See a Few More Opportunities
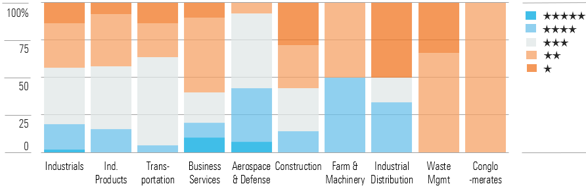
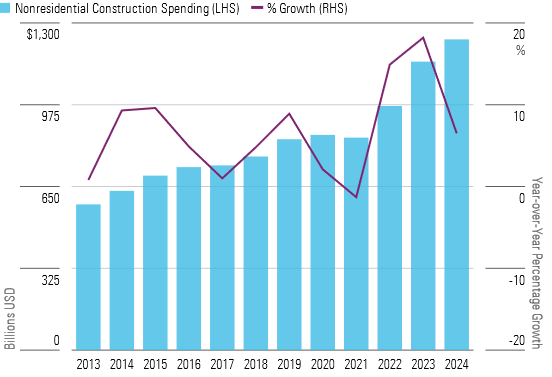
Construction companies with meaningful residential exposure underperformed toward the end of 2024, likely in reaction to the 30-year fixed mortgage rate once again nearing 7%. Affordability remains a key pain point for the US housing market, and higher rates certainly haven’t helped. Nevertheless. Morningstar’s US economics team projects the average 30-year fixed rate mortgage will decline to below 6% in 2025 and reach 5% by 2026. We expect lower rates to revitalize home sales and repair and remodel spending. We believe a healthy pipeline of so-called megaprojects will be a tailwind for construction firms over the coming years.
Megaprojects a Multiyear Tailwind for Nonresidential Construction
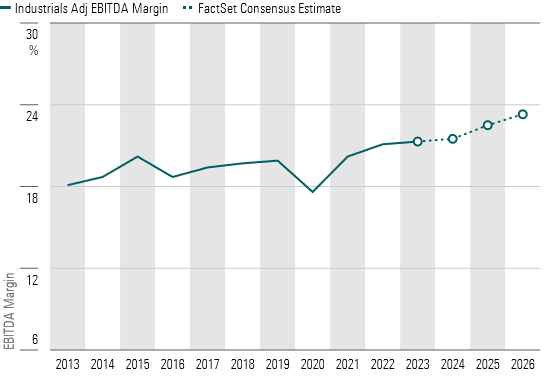
While the industrial sector has more undervalued stocks than it did last quarter, we still see it as broadly overvalued. Many companies have enjoyed growing profit margins over the past several years, and we think the market expects robust profit margin expansion will continue. While we mostly agree with market expectations over the near term, we temper our long-term profit margin projections for many of the firms we cover to consider industry cyclicality, competition, and so on.
Optimistic Margin Expansion Outlook a Risk for Sector Valuations
Top Industrial Sector Picks
A.O. Smith
- Fair Value Estimate: $82.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: Wide
- Morningstar Uncertainty Rating: Medium
A.O. Smith AOS is the largest manufacturer of water heaters in North America. Expansion in foreign markets and water treatment products provides runways for growth. Weaker-than-expected sales in China caused management to reduce 2024 guidance on Oct. 11. However, we expect consolidated sales will rebound in 2025 as demand for water heaters strengthens in North America and the China market begins to recover. The firm’s operating margin should be near 20% over the next few years as China’s housing market recovers and greater scale supports higher water treatment profit margins.
Caterpillar
- Fair Value Estimate: $425.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: Wide
- Morningstar Uncertainty Rating: Medium
Caterpillar CAT is one of the world’s leading providers of heavy construction machinery and a major player in industrial engines and transportation products. Though this is a cyclical business, Caterpillar’s dominant position across its end markets will benefit over the near and medium term from required investments in infrastructure and green energy transitions that are meaningfully increasing its addressable market. In addition to a likely maintainable period of GDP-plus growth, management has pursued accelerated growth in its services business, which has enhanced margins and cash flows while reducing the economic sensitivity of the group.
Huntington Ingalls Industries
- Fair Value Estimate: $326.00
- Morningstar Rating: ★★★★★
- Morningstar Economic Moat Rating: Wide
- Morningstar Uncertainty Rating: Medium
Huntington Ingalls HII is the largest independent military shipbuilder in the United States, generating most of its profits from building ships for the US Navy. The firm’s stock dropped on successive news of delays to submarine deliveries stemming from lagging supply chain and shipbuilding productivity, which hit profit margin along with cost inflation and pre-pandemic contract pricing. The company is negotiating with the Navy for 17 submarines. The Navy may offer flexible pay arrangements for shipbuilders, immediately benefiting the firm’s economics when signed, which is expected to happen in early 2025.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States