
How to Maximize the Tax Efficiency of an ETF Portfolio
Selecting the proper vehicle for each type of investment is key.
Index exchange-traded fund investors often have little to worry about regarding the tax implications of their investments, but there are still more ways to maximize the tax efficiency of an ETF portfolio. Thinking about asset location—the most tax-efficient way to distribute different investments across different types of accounts—is the logical next step after selecting the ETFs you want to own.
All I Want for Christmas Is a Tax-Advantaged Account
The first part of our puzzle involves figuring out the tax characteristics of different account types. In the US, multiple tax-advantaged accounts are available to investors, with options to grow their investment either tax-deferred or tax-free. Exhibit 1 provides a quick overview of the most popular tax-advantaged accounts.
Tax-Advantaged Accounts
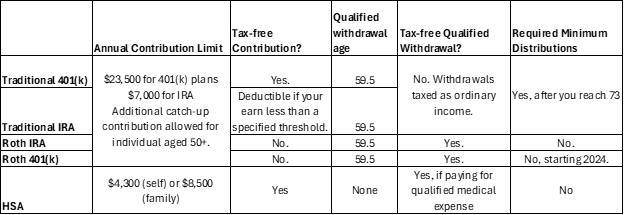
Both 401(k)s and IRAs come in traditional or Roth form. The choice depends on the difference in your current tax rate and your expected tax rate when you start withdrawing money. Traditional accounts let you contribute pretax money and pay ordinary income tax once you withdraw the funds. In contrast, Roth accounts are funded by aftertax dollars, meaning accountholders have no tax liability from withdrawing funds so long as they exceed the requisite withdrawal age. Given the difference between when the money is taxed, choosing between traditional and Roth accounts comes down to timing tax liabilities. Traditional accounts can be beneficial if you’re currently in a high tax bracket and expect a lower tax rate down the line. In contrast, Roth accounts can be beneficial to those currently at a lower tax bracket. Either way, these accounts have an advantage over a taxable brokerage account where you pay tax on your contributions as well as any income or gains as realized.
For investors who plan to retire in the US and start withdrawing money after the age of 59.5, it’s a good idea to max out annual contributions to tax-advantaged accounts, if possible. The annual limit is higher for 401(k) plans than an IRA account, and investors aged 50 or older can contribute an additional $1,000 to their IRA and $7,500 to their 401(k).
One caveat is your health savings account, where the tax savings apply only if you’ll be using the withdrawal for qualified medical expenses, which includes most healthcare expenses from doctor visits to medically necessary procedures. Justifying setting aside a large sum of money in your HSA depends on personal circumstances and may not be for everyone.
A taxable brokerage account works well for money you may need before reaching 59.5 years old. Tax-advantaged retirement accounts levy a 10% early withdrawal penalty, so money in those accounts should be the last resort before reaching the appropriate age. There are a few exceptions, such as qualified education expenses, childbirth, or unemployment health insurance. Roth contributions that were already taxed can be withdrawn without penalty, though this means forgoing future tax-free gains on your principal.
How ETFs Help You Cut Your Tax Bill
Asset Location Best Practices
Given the varying tax treatments across these accounts, the second part of our puzzle is figuring out which investment is best suited for which account. Stocks tend to be more tax-efficient than bonds, as a rule of thumb. A higher portion of stocks’ returns come from capital appreciation, which can benefit from a lower tax rate for long-term capital gains. Qualified dividends can may also enjoy a lower tax rate. In comparison, most of bonds’ returns come from interest income and get taxed at the ordinary income rate. As a result, investors should start by allocating bonds to tax-sheltered accounts and leaving stocks in taxable ones.
Selecting the proper vehicle for each type of investment is the next step. ETFs are the most efficient vehicle given their ability to defer taxes by avoiding capital gains distributions by the fund. Passive or active, ETFs have had a much better track record than their mutual fund counterparts so far. Nonetheless, ETFs must still pass through taxable interest income or dividends to their investors, so some investments will stick you with a larger bill than others.
- In general, interest income on bonds is taxed at the higher ordinary income tax rate. On the other hand, dividends can enjoy the lower qualified dividend tax rate if held for a specific period before the ex-dividend date. Many stock fund providers aim to maximize the qualified dividend portion of their payout, especially passive ETFs that mostly keep their holdings stable over time.
- Not all bond ETFs create the same tax drag. Treasury ETFs (or broad bond ETFs holding Treasuries) are exempt from state and local taxes, and their relative lower yield compared with corporate bonds often leads to a lower tax bill. Municipal bonds are exempt from federal income taxes, and often state taxes in the state they were issued. They might carry a lower yield to account for this tax advantage, however. Depending on your effective tax rate, the aftertax equivalent yield on a taxable-bond ETF may be higher or lower than a municipal-bond ETF.
- On the other hand, ETFs holding high-yielding asset classes such as high-yield corporate bonds or REITs can pay out sizable taxable distributions. ETFs using derivatives, such as covered-call ETFs holding index options or equity-linked notes, are also required to pay out some short-term capital gains or interest income.
Generally, investors should park these less tax-efficient investments in a tax-advantaged account and keep tax-efficient funds for their taxable accounts. Consider a traditional 60/40 allocation with 40% US stocks, 40% bonds, and 20% international stocks:
- Park the bond portion in a tax-sheltered account owing to their higher tax drag. Roth accounts are better reserved for investments with the highest potential for growth given their tax treatment, so in most cases a traditional 401(k) or IRA is a good place for your bond funds. Ultimately though, the choice between traditional versus Roth accounts will depend on your expected future tax rate, as mentioned earlier.
- Allocate your most aggressive stock funds to your Roth IRA or 401(k), as it has the highest earning potential. It can grow tax-free in these accounts and avoid capital gains tax on the large price appreciation over its lifetime (when making qualified withdrawals). Roth accounts are also not subjected to a required minimum distribution unlike a traditional 401(k) or IRA. This helps avoid forced liquidation on some of your highest-growth positions.
- Park the rest of your stock allocation in any of your tax-advantaged accounts, especially any high-dividend stock funds.
- Your taxable account is best used to house your most efficient stock funds. Think of your broad US large-cap or total-market stock ETFs with low dividend yields and few capital gains distributions. If you must hold bonds in a taxable account, consider municipal-bond ETFs.
What if you don’t want to manage investments and instead prefer a target-date fund?
Many investors opt for target-date funds that hold multiple asset classes for their simplicity and convenience. Their time savings and inherent investment discipline can be more beneficial than tax savings for some investors. If possible, it’s best to place them in a tax-advantaged account like a traditional 401(k) since these funds pay both interest income from bond holdings and capital gains from rebalancing their stock sleeves. Though a Roth IRA or 401(k) might be better reserved for high-growth assets, parking a target-date fund here isn’t necessarily a bad idea for investors in their accumulation phase where their target-date funds will likely hold a hefty proportion of stocks.
A Quick Word About Tax-Loss Harvesting
With the rise of robo-advisors and direct indexing in recent years, tax-loss harvesting has risen in popularity as a tax-saving strategy. Tax-loss harvesting refers to selling losing investments to generate capital loss. That loss can be used to offset expected capital gains from other positions or up to $3,000 in taxable income per year, or it can be carried forward indefinitely to offset future gains. However, you cannot simply buy back the losing investment immediately, as the IRS wash sale rule prohibits selling at a loss and buying a substantially similar security within 30 days. Nonetheless, you can use this strategy to work out of concentrated positions or to change the overall allocation of your portfolio. Many robo-advisor services swap out one ETF with another highly correlated one to avoid altering the portfolio’s investment profile while taking losses. This requires different enough exposures to get around the wash sale rules. Consult with a tax professional about the specific investments if you’re considering doing it yourself.
It’s also worth noting that doing this will decrease the cost basis of the position and will decrease your opportunity to tax-loss harvest in the future. At some point, you do have to pay taxes on gains.
This article appeared in the December 2024 issue of Morningstar ETF Investor. For a free sample issue, click here.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States