
Why Are We Updating Our Medalist Rating? Simpler Is Better
We’re making it clearer how we evaluate expenses and streamlining the rating’s algorithmic components.
Morningstar announced on Dec. 4 that it’s simplifying its Medalist Rating.
What Is the Morningstar Medalist Rating?
The Morningstar Medalist Rating is a forward-looking assessment of mutual funds, exchange-traded funds, and other managed investments, including semiliquid funds and 529 college savings plans. Gold, Silver, and Bronze ratings are given to funds that Morningstar expects to outperform the category benchmark over a full market cycle. Morningstar assigns Medalist Ratings to more than 350,000 share classes globally as of November 2025.
Currently, to arrive at a Medalist Rating, Morningstar analysts—or an algorithm, if an analyst isn’t assigned to cover the fund—assess three fundamental pillars to determine whether outperformance is likely: People, Process, and Parent. The People Pillar encompasses the managers and analysts making a fund’s key investment decisions. The Process Pillar considers the effectiveness and repeatability of its investment strategy, while the Parent Pillar is an analysis of the offering firm and whether it puts fund investors’ interests before its own.
Morningstar combines a fund’s fundamental pillar assessments and, together with its price and likelihood of outperforming its category benchmark index, awards it a Gold, Silver, Bronze, Neutral, or Negative rating.
What’s Changing About the Medalist Rating?
In April 2026, we’ll make a few changes to better illustrate how we evaluate a fund’s expenses and how we arrive at the final Medalist Rating. We’re also updating the way we calculate the rating’s algorithmic components, which we use when an analyst doesn’t rate each pillar.
Specifically, we are:
- Simplifying the rating’s structure
- Taking a category-relative approach
- Creating new quantitative calculations
- Assigning medals with fixed rating thresholds
Before diving into the details, here’s what’s staying the same: Morningstar’s 130 global researchers will continue to qualitatively rate more than 3,200 fund strategies’ fundamental pillars in the same transparent manner they have used for decades. The analysts’ structured, well-documented, and peer-reviewed process provides a consistent basis for assessing investment quality and distinguished funds with stronger characteristics on a forward-looking basis.
A Simplified Structure
The simplified Medalist Rating will make funds’ future performance drivers relative to their category peers clearer and highlight which funds can outperform their peer group averages.
We’ll continue to display People, Process, and Parent Pillar ratings as High, Above Average, Average, Below Average, and Low. We’re further enhancing the rating by displaying a Medalist Rating Price Score, or MPS, of negative 2.5 to 2.5 to illustrate whether a fund’s fee is a competitive advantage or significant headwind. The MPS will boost low-cost funds’ ratings, while discounting those of expensive funds, which empowers investor success because fees are often the best predictor of future performance.
The new approach will apply straightforward weights to each rating component and sum them to determine the fund’s Medalist Rating. Component weights will differ for actively managed funds and passively managed funds to reflect how those strategies are managed and generate returns.
The New Simplified Medalist Rating Input Weights
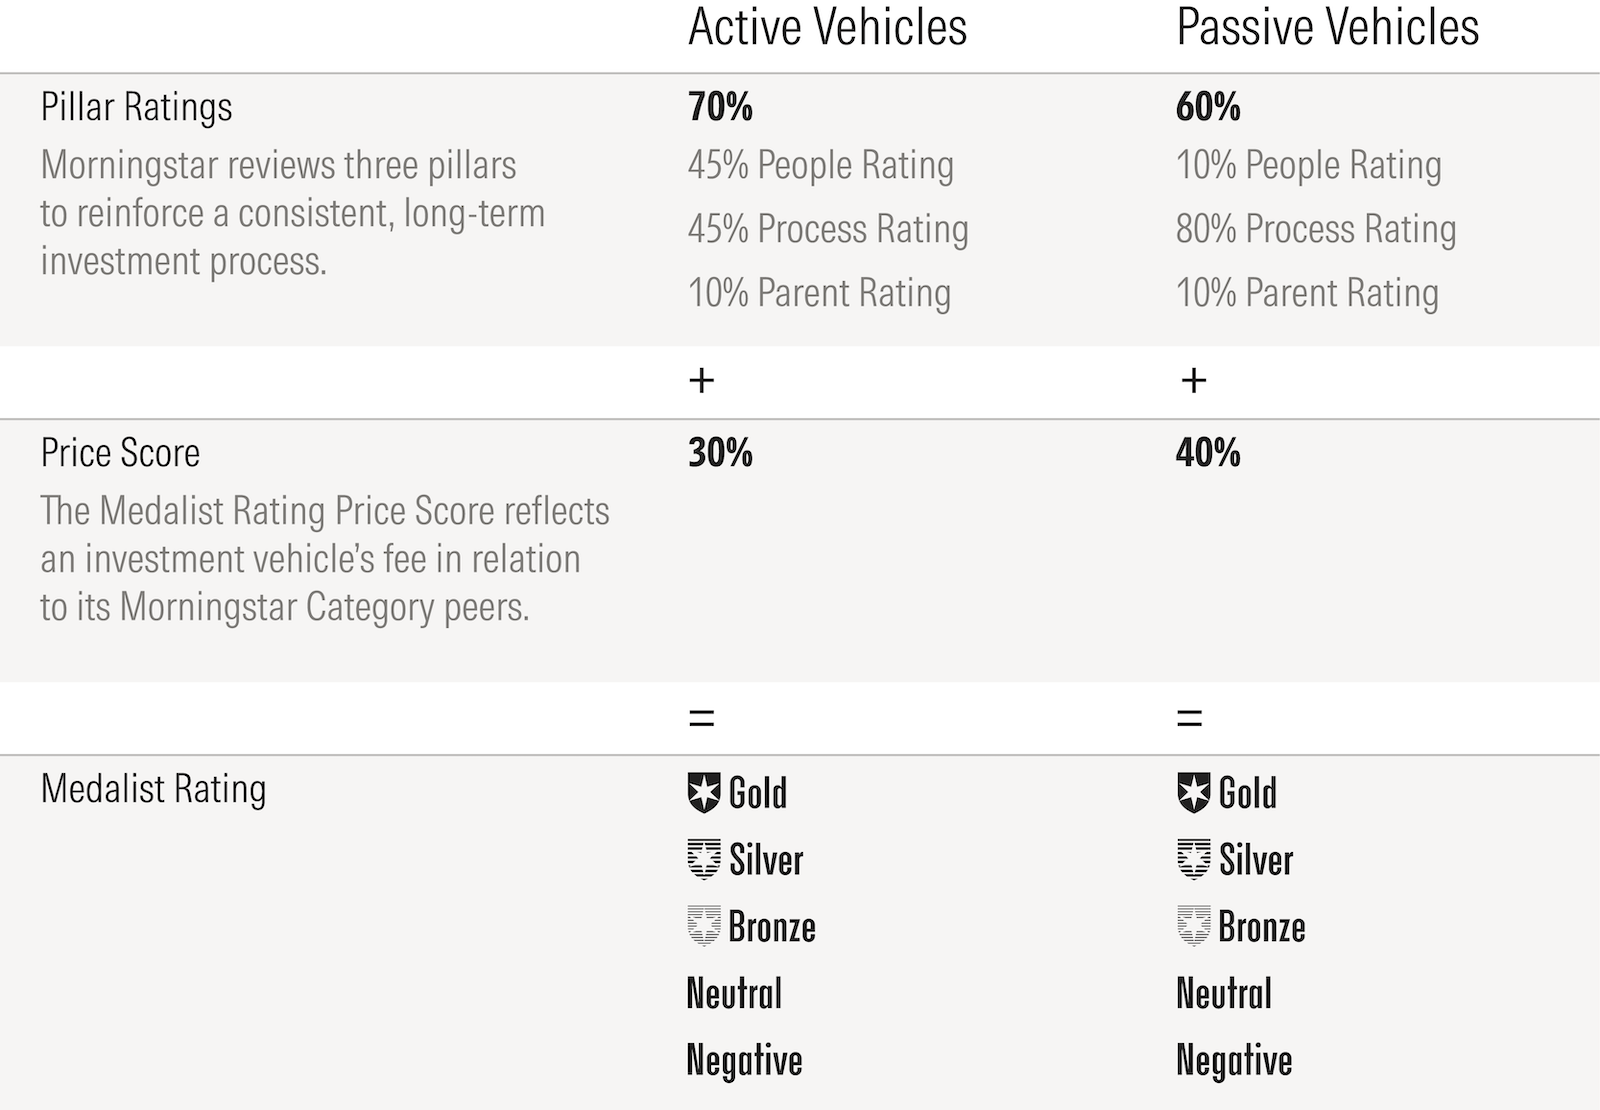
Here’s an example of how the fundamental pillars and MPS will be displayed for a few share classes of a US large-growth equity fund:
Taking a Category-Relative Approach
We’re no longer going to factor into the ratings calculation the degree to which a category’s funds had been able to generate alpha in the past relative to their category index. The current methodology assumed every fund in a category aimed to beat the Morningstar-assigned benchmark.
The category benchmark’s asset allocation and/or sector weights differ significantly from the typical fund’s in many multi-asset allocation, noncore equity, and fixed-income peer groups, making a category benchmark test less relevant than peer-to-peer comparisons. So, our revised approach will measure Medalists versus their category averages, rather than their category benchmarks.
More-Transparent Inputs
Of the 175,000 traditional fund and ETF share classes that received a Medalist Rating on Nov. 21, 2025, about 150,000 rely on an algorithm to provide at least one pillar score when an analyst hasn’t rated it directly. Our current approach uses a machine-learning model to generate these ratings by mimicking how analysts set scores. While the model effectively identifies funds likely to perform well, its adaptive nature makes it difficult to pinpoint which data influenced a fund’s Medalist Rating.
Starting in April 2026, the algorithmic pillar methodology will use clearer and more-transparent input data. We’ll show simple calculated data points that reflect how a Morningstar analyst would assess each pillar. For example, analysts look at managers’ experience when evaluating the People Pillar. The model will now include a new data point—Fund Manager Successful Experience—to measure which funds are run by managers with a proven ability to outperform across their career. This will help determine the People Pillar rating.
For active funds’ Process Pillar ratings, the algorithm will consider their information ratio, or their cumulative return divided by their tracking error relative to their index. The assessment also includes data that measures style drift and volatility, as well as the firm’s past success at delivering outperformance within the fund’s asset class.
The algorithmic Parent Pillar will consider the fees, manager tenure and retention, performance, and survival and obsolete rates of an asset manager’s full fund lineup.
For passively managed funds, the Process Pillar carries the most weight in determining the Medalist Rating. The algorithmically generated pillar will stress the historical ability of passives to outperform actives in a category, volatility of their excess returns versus the category index (tracking error), and concentration risk among portfolios’ top holdings, among other measures.
This simplified quantitative methodology will make it easier to identify which data contributed to a fund’s Medalist Rating and how. We will continue to mark algorithmic pillars with a superscript Q in our data displays and reports.
Assigning Medals With Fixed Rating Thresholds
The updated methodology does away with the Medalist Rating’s existing forced distribution curve, which has limited the number of Gold-, Silver-, and Bronze-rated funds in each category. The curve has been replaced by fixed thresholds. We expect the simplified approach, including the long-term nature of the data behind the algorithmic pillars, will create a more stable set of ratings.
We understand investors monitor their funds’ Medalist Ratings and have questions when ratings change. The simplified approach will increase stability by eliminating a forced distribution of ratings that caused ratings to change based on updates to other funds.
Implementing the Simplified Methodology
We plan to roll out the changes in April 2026. We’ll apply the new fixed-threshold scores to all funds at once, to make easy comparisons. When we apply the updated calculations to existing Medalist Ratings, we see fewer Bronze, Neutral, and Negative ratings and more Gold and Silver ratings relative to the existing methodology. That doesn’t mean it’s going to be easy to get a Gold, Silver, or Bronze rating: Less than 30% of the existing ratings are expected to translate to a better-than-Neutral medal under the updated methodology.
Medalist Rating Global Distribution: New vs. Current Methodology
Want to Learn More?
If you have questions about the methodology enhancements, check out the full methodology and data definitions. Or, you can ask me or other research and product leaders any questions at our upcoming webinar.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States