
Financial Services: The Benefits of a Steep Yield Curve Are Largely Already Priced In
Our top picks in this sector include MarketAxess and PayPal.

While many companies in the financial services sector benefit from a steeper yield curve, we believe much of those benefits are already priced in. Companies with long-duration, interest-yielding assets earn higher revenue when long-term interest rates are high. Companies with most of their interest-bearing liabilities tied to short-term interest rates reduce one of their main costs of generating revenue when short-term interest rates are low. Given the movement of interest rates in the recent quarter and the Federal Reserve’s assessment of appropriate monetary policy, a steeper yield curve will likely persist for the foreseeable future.
A Steeper Yield Curve Has Recently Increased Financial Sector Performance
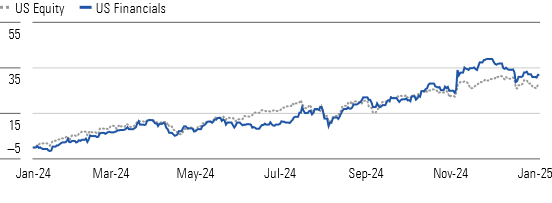
Financial Sector Valuations Look Rich as a Steeper Yield Curve Is Priced In

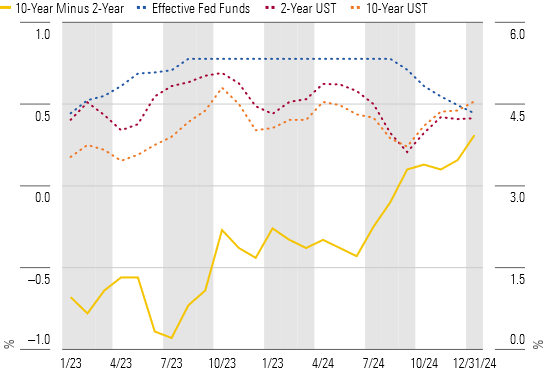
There’s been a steepening of the yield curve (as measured by the yield on the 10-year US Treasury minus the yield on the two-year US Treasury), with the monthly average yield curve turning positive in September and then becoming much more positive as the Fed began lowering the federal-funds rate and the 10-year US Treasury yield started climbing.
The Yield Curve Has Significantly Steepened
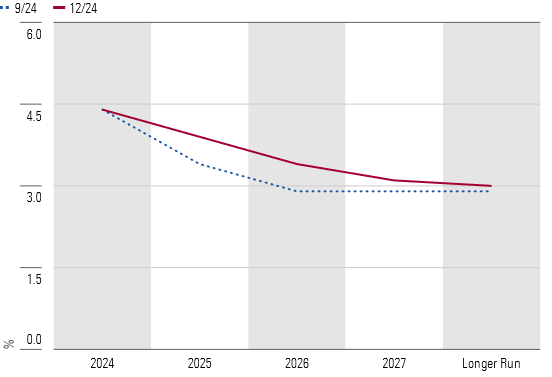
Noticeable changes in interest-rate expectations occurred in the past couple of months. We see a Republican sweep on Congress as more beneficial to financial stocks, thanks to less-strict banking regulation, historical comfort with approving mergers, and more positive sentiment on cryptocurrencies. The Federal Open Market Committee also had a meeting in December and released its assessment that the federal-funds rate would be cut 50 basis points in 2025, compared with a prior expectation of 100 basis points, due to higher current and expected core inflation.
The Federal Reserve Expects Fewer Interest Rate Cuts in 2025 than Before
While we believe that many companies in the financial services sector are overvalued, if the yield curve steepens more or stays steep longer than the market anticipates without the US falling into a recession, there could be further upside to the financial sector.
Top Financial Sector Picks
MarketAxess Holdings
- Fair Value Estimate: $305.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: Wide
- Morningstar Uncertainty Rating: High
We expect 2025 to be a better year for growth for MarketAxess MKTX, as last year, the company faced dual headwinds from both low corporate bond issuance levels and an unfavorable mix shift creating downward pressure on its average fees. While these headwinds are still a factor, the company is benefiting from higher trading volume industrywide, and if interest rates fall, the company will see some relief for its average pricing. That said, MarketAxess continues to face significant competition in the electronically traded US corporate bond market from both Tradeweb TW and the smaller Trumid, which has led its investment-grade bond market share to be relatively stagnant in recent years. We still see meaningful secular growth drivers for MarketAxess, but competition will be a headwind to volume growth.
PayPal Holdings
- Fair Value Estimate: $104.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: Narrow
- Morningstar Uncertainty Rating: High
PayPal’s PYPL shares have fallen about 75% from their pandemic peak to materially below their pre-pandemic price. With market confidence in the stock at a low ebb, we see a potentially good long-term opportunity. While we recognize the headwinds PayPal faces in the near term, in the long term, the company’s fate remains tied to the high-growth e-commerce space, with Venmo providing some additional upside option value. Historically, PayPal has demonstrated it can take shares in this area, and we think it continues to do so on an overall basis. We believe the company retains a strong competitive position.
U.S. Bancorp
- Fair Value Estimate: $53.00
- Morningstar Rating: ★★★
- Morningstar Economic Moat Rating: Wide
- Morningstar Uncertainty Rating: Medium
We believe there are still some pockets of opportunity in the banking industry. The biggest risk to our top banking picks would be surprises on deposit and funding costs or the realization of a recession. U.S. Bancorp USB has sold off like some of the regionals, but we see relatively lower risk for the company, since it’s the largest regional. The bank does have slightly higher-than-average unrealized losses on securities, but we view this more as an earnings problem (lower-yielding assets stuck on the balance sheet) and not a capital problem.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States