
Healthcare: Sector Looks Undervalued with Pullback After US Election and Obesity Data
CVS Health and Moderna are some of our favorite stocks in this sector.


Over the past 12 months, overall US equity has outperformed the Morningstar US Healthcare Index by over 25 percentage points. The sector’s more defensive nature likely led to underperformance early in the year and outperformance in the third quarter as recession concerns ebbed and flowed, but its derailment in the fourth quarter was largely tied to post-election uncertainties and disappointing news for large-cap biopharma and healthcare plan (managed-care) stocks.
Healthcare Underperformed the US Market in 2024, with a Particularly Weak Q4
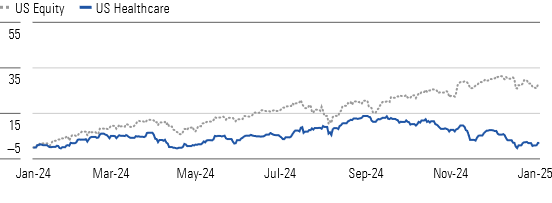
Following a rough fourth quarter, we see the healthcare sector overall as undervalued, with a median discount to our fair value estimates of more than 10%. Medical distribution stands out as the only overvalued industry, while plans and biopharma look the most undervalued.
Apart from Distribution, Healthcare Industries Look Undervalued
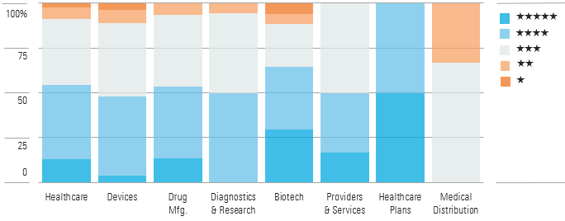
We expect the more defensive nature of the sector to continue to support it if economic concerns arise, although uncertainty around healthcare policy is heightened under the incoming Republican administration. Within biopharma, the market is not fully appreciating innovation beyond obesity leaders Eli Lilly LLY and Novo Nordisk NVO. We think new government leadership is unlikely to create significant new approval or pricing headwinds in biopharma, which is still digesting Medicare reforms as part of the Inflation Reduction Act. In managed care, we think shares look undervalued even in some of the more bearish scenarios for policy reform under a new Republican-led administration. Device and diagnostic valuations are still stabilizing after falling from a period of over-optimism during the peak of the covid-19 pandemic.
US Biopharma Firms Have Varying (but Significant) US Market Exposure
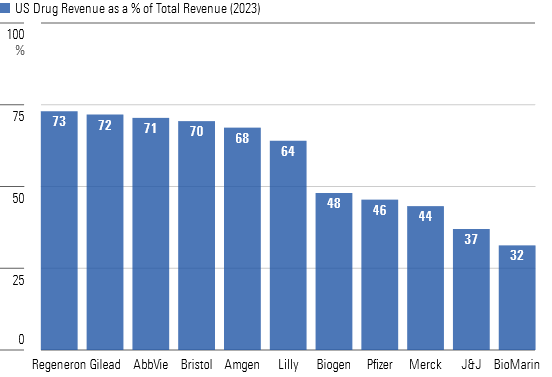
Trump’s win in the US presidential election and Republican control of Congress could pressure US healthcare growth, and most global biopharma firms have significant US exposure. However, we see a low probability of major reforms. We continue to see Novo and Lilly as dominating a potential $200 billion GLP-1 market by 2031. However, their shares have traded down on near-term growth concerns and mixed data for Novo’s next-generation drug CagriSema, leaving the door open for future challengers.
Global GLP-1 Market Driven by Novo Nordisk, Eli Lilly, and New Challengers
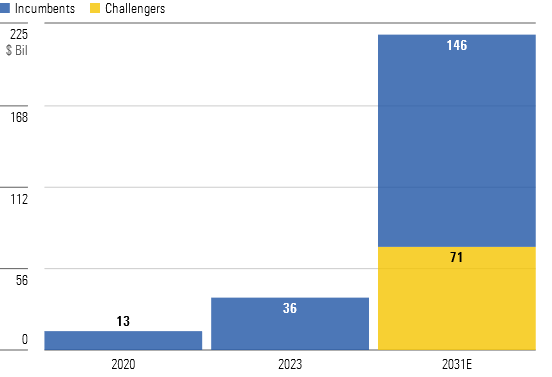
Top Healthcare Sector Picks
Baxter International
- Fair Value Estimate: $62.00
- Morningstar Rating: ★★★★★
- Morningstar Economic Moat Rating: Narrow
- Morningstar Uncertainty Rating: High
Demand is improving in most of Baxter’s BAX medical supply businesses because of rising medical utilization, and new products like the Novum IQ pump platform could boost growth. Baxter also represents a margin improvement story, as most inflationary challenges in its supply chain are easing. Additionally, key new group purchasing organization contracts should take effect this year, which should help boost product pricing. The pending sale of its kidney care segment came through at a low price, and related costs will slightly weigh on margins through 2026, but we expect management focus on growth and margins for the remaining business could boost shares.
CVS Health
- Fair Value Estimate: $93.00
- Morningstar Rating: ★★★★★
- Morningstar Economic Moat Rating: Narrow
- Morningstar Uncertainty Rating: Medium
CVS CVS shares trade at a steep discount to our fair value estimate, due to market concerns around its Medicare Advantage business and potential new regulatory headwinds—particularly on its pharmacy benefit management business—as Republicans take control in 2025. However, we see room for improving Medicare Advantage profits starting in 2025, as the company should benefit from the return of star rating-related bonus payments after a dismal 2024. We think CVS shares would be undervalued even in some of the most negative regulatory scenarios, which we suspect face a low probability of approval. Overall, with CVS trading at just 8 times its 2024 deflated earnings and the firm’s dividend yielding about 6%, we think shares could rebound substantially if new management can guide a turnaround.
Moderna
- Fair Value Estimate: $141.00
- Morningstar Rating: ★★★★★
- Morningstar Economic Moat Rating: None
- Morningstar Uncertainty Rating: Very High
We think Moderna MRNA investors were overly enthusiastic about the potential of the company’s mRNA technology during the pandemic and subsequently have been too bearish on its post-pandemic growth. While we have modest expectations for sales of the firm’s covid-19 vaccine following massive pandemic-fueled demand in 2021 and 2022, we think Moderna’s pipeline of mRNA-based vaccines and treatments is advancing rapidly across multiple therapeutic areas. We’re confident in the long-term sales trajectory of the company’s diversified pipeline, despite a competitive RSV vaccine market clouding near-term prospects.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States