
5 Stocks With the Largest Fair Value Estimate Cuts After Q2 Earnings
Intel and Lyft are among the names with the deepest reductions to their valuation estimates.
While second-quarter earnings were largely positive for the 874 US-listed stocks covered by Morningstar analysts, some companies had their fair value estimates slashed.
Among the stocks on Morningstar’s list, the average change in fair value estimate was a 0.77% increase, below the 10-year average increase of 1.45% per earnings season. Of those 874 stocks, about 3% saw their fair value estimates cut by a meaningful amount of 10% or more.
Fastly FSLY saw the largest fair value cut for the second quarter in a row. Slowing demand and reduced full-year revenue guidance have created concern that the company is at a competitive disadvantage against its peers, according to Morningstar’s Matthew Dolgin.
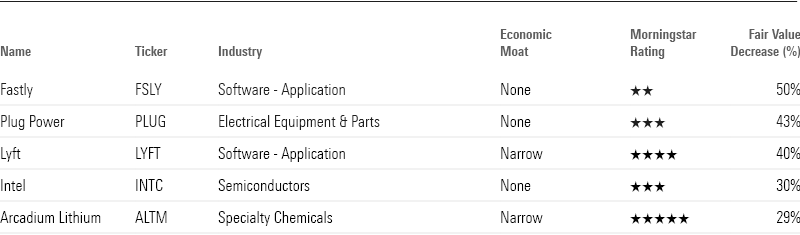
Stocks With the Largest Fair Value Estimate Cuts
- Fastly FSLY: $5 per share from $10
- Plug Power PLUG: $2.00 per share from $3.50
- Lyft LYFT: $15 per share from $25
- Intel INTC: $21 per share from $30
- Arcadium Lithium ALTM: $10 per share from $14
A large cut or increase in a fair value estimate may signal to investors that a company’s fortunes are changing. However, it’s important to consider how a stock trades compared with the estimate. Both Lyft, which has a Morningstar Rating of 4 stars, and Arcadium Lithium, which has a 5-star rating, are trading below their estimates, meaning our analysts think they’re attractively priced for long-term investors. This holds even after their big valuation cuts.
Stocks With the Largest Fair Value Cuts
Here’s what Morningstar’s analysts had to say about these stocks.
Fastly
- Fair Value Estimate: $5.00
- Fair Value Decrease: 50%
- Economic Moat: None
- Morningstar Uncertainty Rating: Very High
Fastly had the largest fair value estimate cut, going to $5 from $10. “Fastly’s second-quarter results fell neatly into the guidance it had given, but management materially reduced its full-year guidance for the second straight quarter, and it is continuing to see demand problems from its biggest customers,” wrote Dolgin.
“Management’s concern about the revenue trend led it to implement a restructuring to take costs out of its business. It feels like the company is in crisis, and we question whether it can make these moves to preserve near-term results without dampening the long-term growth outlook that was imperative to justify the firm’s valuation. We’re not implying these are the wrong moves; we suspect they’re absolutely necessary. However, we think Fastly will have difficulty returning to the high teens growth trajectory it had been on.”
Fastly is trading at a 29% premium to its new fair value estimate and has a Morningstar Rating of 2 stars.
Investors can find more of Dolgin’s take on Fastly here.
Plug Power
- Fair Value Estimate: $2.00
- Fair Value Decrease: 43%
- Economic Moat: None
- Morningstar Uncertainty Rating: Extreme
Plug Power saw its fair value estimate cut to $2.00 from $3.50 due to reduced long-term revenue and margin forecast. “Plug Power’s second-quarter results saw a continued focus on cash management over revenue,” wrote Morningstar equity analyst Brett Castelli. “Revenue was down 44% year on year because of lower equipment sales. Gross margins remained sharply negative, although the company made progress on fuel and service margins. Based on management guidance, Plug expects a steep ramp in revenue in the second half, with approximately 70% of full-year revenue coming in the next two quarters.”
Castelli continues: “Plug ended the quarter with $62 million in unrestricted cash, but this number was increased with the July 19 share offering, which netted the company approximately $200 million. We expect the company to look to continued equity issuance, inventory reductions, and a Department of Energy loan to provide additional near-term liquidity while operating results improve. The company has raised approximately $572 million via equity issuance through June 30. We think Plug is taking necessary steps to minimize the cash burn, including cost savings and improving margins via raising prices. However, the company’s liquidity remains constrained. Additional financing will continue to be needed over the coming quarters as we expect operating losses to continue in 2025.”
Plug Power is trading near its new fair value estimate and has a Morningstar Rating of 3 stars.
Take a deeper dive into Castelli’s outlook for Plug Power.
Lyft
- Fair Value Estimate: $15.00
- Fair Value Decrease: 40%
- Economic Moat: Narrow
- Morningstar Uncertainty Rating: Very High
Lyft saw its fair value estimate slashed to $15 from $25. “Driving most of our fair value revision is an updated growth outlook for the firm’s gross bookings and its revenue in the near-to-medium term,” wrote Morningstar equity analyst Malik Ahmed Khan. “We believe that while Lyft’s topline has been decelerating in recent quarters, a more pronounced deceleration could occur in 2025. We expect macro concerns in 2025, including a weakening job market, along with increased competition from Uber, will drive customers away from the firm’s platform. Further, while we view the entrance of AV, or autonomous vehicle, fleets as a potential advantage for Uber, which can build partnerships with AV firms to provide its ridesharing expertise, the same cannot be said about Lyft due to the firm’s limited scale. With the firm’s shares trading down sharply after reporting results, we continue to view Lyft as moderately undervalued relative to our updated fair value estimate.”
Lyft is trading at a 22% discount to its new fair value estimate and has a Morningstar Rating of 4 stars.
Read Khan’s full take on Lyft here.
Intel
- Fair Value Estimate: $21.00
- Fair Value Decrease: 30%
- Economic Moat: None
- Morningstar Uncertainty Rating: High
Intel saw its fair value estimate cut to $21 from $30. “Intel reported disappointing second-quarter results while providing investors with a gloomy third-quarter forecast, suspending its dividend, and outlining a hefty cost-cutting program considering softer demand,” wrote Morningstar equity strategist Brian Colello.
“Intel’s stock fell as much as 20% after hours, and we think the severe negative reaction was justified. We have cut our fair value estimate to $21 from $30 and do not see the selloff as a buying opportunity, as we are concerned about Intel’s competitive positioning. Even though Intel is doing the proper work to focus on leading-edge chip manufacturing, it appears many of its customers in various end markets might be leaving Intel behind.”
Intel is trading near its new fair value estimate and has a Morningstar Rating of 3 stars.
Colello has more about Intel’s stock here.
Arcadium Lithium
- Fair Value Estimate: $10.00
- Fair Value Decrease: 29%
- Economic Moat: Narrow
- Morningstar Uncertainty Rating: Very High
Aracadium saw its fair value estimate drop to $10 from $14. “In Arcadium’s second-quarter results, the second since the company was created in the Livent-Allkem merger, adjusted EBITDA declined 9% sequentially versus the first quarter, as lower lithium prices were partially offset by higher volumes,” wrote Morningstar equity strategist Seth Goldstein. “Management announced capital expenditure reductions and cost-cutting initiatives in response to lower lithium prices. Most notably, the company signaled it would pause the Galaxy spodumene project and delay construction on the Sal de Vida project as a way to reduce capital expenditures in 2024 and 2025.”
Goldstein adds: “We view current prices as offering a strong margin of safety with a lower-for-longer lithium price scenario already priced into the stock. For long-term investors, we view Arcadium as a strong pick given the company’s low-cost Argentina production, strong balance sheet, and positive free cash flow generation during the first half of the year. With far lower capital expenditures and a focus on running the company’s low-cost lithium operations, we expect Arcadium will maintain a strong balance sheet through what we view as a cyclically low period for lithium prices.”
Arcadium is trading at a 71% discount to its new fair value estimate and has a Morningstar Rating of 5 stars.
The rest of Goldstein’s take on Arcadium can be found here.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States