
Utilities: Rally Slowed in Summer, but the Sector Is Still Beating the Market Year to Date
Eversource, Duke, and Edison are our preferred stocks in this sector.
Utilities’ remarkable run since late 2023 stalled this summer—a pullback we think was long overdue. The Morningstar US Utilities Index remains up 70% from its low in October 2023, including dividends, outperforming every sector except technology. But since the utilities index peaked in early August, utilities are one of only two sectors that are down.
US Utilities Rally Tapers Off in Third Quarter
The reversal comes despite a dovish turn in interest rates and weaker economic data—both typically bullish developments for utilities stocks. Investors’ lackluster response validates our view that the sector’s valuations have become too frothy.
Market’s Lofty Growth Expectations Have Inflated Many Utilities’ Valuations
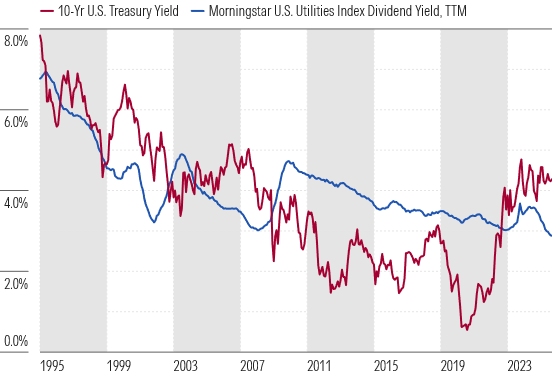
Utilities’ valuations remain historically high, and we think there is more downside to come. We consider the sector overvalued as of late September. In addition, utilities’ 3% average dividend yield is among the lowest in history. This suggests that investors are valuing utilities more for their growth than their income, a huge shift from their typical investment profile. The low yields give investors little protection if utilities’ growth prospects disappoint.
Utilities’ Dividend Yields Are Rarely This Low Relative to Interest Rates
We continue to expect 6% annual earnings growth for most utilities through 2030 based on secular trends such as clean energy growth, data center energy demand, manufacturing onshoring, and economywide electrification. Most utilities are planning for the most energy demand growth and capital investment over several generations. If this growth continues and utilities stocks pull back further, investors should be ready to buy.
Data Center Demand Expected to Increase Threefold by 2035
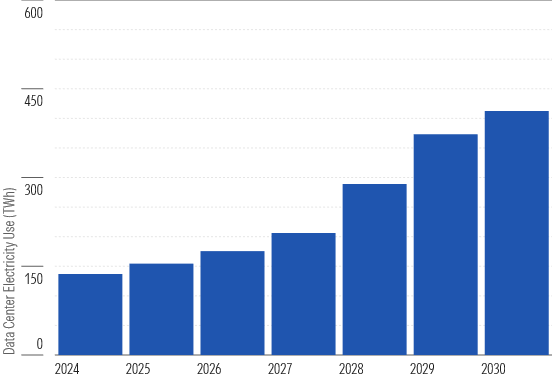
Utilities’ 3% average dividend yield remains historically low on an absolute basis and relative to interest rates. Investors’ growth expectations could dampen any prospect for higher yields regardless of how interest rates move in the near term. We expect interest rates to remain above utilities’ dividend yields, provided the market expects elevated earnings growth, notably from new data center energy demand. Electricity use is up 3% through July, and we expect that growth to accelerate as more data centers come online.
Top Utilities Sector Picks
Eversource Energy
- Fair Value Estimate: $73.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: None
- Morningstar Uncertainty Rating: Low
Eversource EVS will miss out on most of the data center growth excitement but has plenty of investment opportunities in transmission and distribution to support at least 6% annual earnings growth, at least through 2028. We think the Trump administration’s opposition to offshore wind ultimately won’t have a significant impact on Eversource despite the nearterm uncertainty. We think Eversource can offset regulatory challenges in Connecticut by adding projects in Massachusetts, where regulation is more constructive. A turnaround in Connecticut offers earnings and valuation upside. Eversource’s balance sheet leverage should be back to normal range by the end of this year.
Duke Energy
- Fair Value Estimate: $121.00
- Morningstar Rating: ★★★
- Morningstar Economic Moat Rating: Narrow
- Morningstar Uncertainty Rating: Low
Duke DUK has a clear pathway to achieving the high end of management’s 5%-7% annual earnings growth target supported by the company’s regulated subsidiaries. Duke’s $87 billion capital investment plan for 2025-29 is focused on clean energy, grid infrastructure upgrades, and supporting load growth. We don’t think the market appreciates the upside to Duke’s capital plan and additional electricity demand growth from data centers. In North Carolina, Duke’s most important jurisdiction, regulation has improved significantly due to recently passed legislation.
Edison International
- Fair Value Estimate: $80.00
- Morningstar Rating: ★★★★★
- Morningstar Economic Moat Rating: Narrow
- Morningstar Uncertainty Rating: Medium
Edison’s EIX stock remains down 30% since the January fires despite positive regulatory and political developments this summer. We expect Edison will be able to access California’s $21 billion AB 1054 Wildfire Fund for Eaton fire liabilities and the recently enacted $18 billion expansion for future fire liabilities, resulting in minimal shareholder losses. Investments in safety and widespread electrification to meet California’s 2045 carbon-neutral target support our 7% average annual earnings growth outlook, at the high end of management’s 5%-7% target.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States