
Utilities: Stocks Still Climbing From Late-2023 Bottom
Our top picks in this sector are Duke, Eversource, and Edison.
Nothing seems to stop US utility stocks from delivering impressive returns recently. After utilities jumped 26% in 2024, including dividends, the sector has climbed another 12% through the first half of 2025. In total, utilities are up 60% from their low point in October 2023, outperforming the US Market Index by more than 15 percentage points. If these returns hold through this summer, it would mark the sector’s best two-year relative performance since 2008.
US Utilities Stock Rally Has Continued Through the First Half of 2025

What is most remarkable about this rally is that it hasn’t coincided with significant moves in interest rates and inflation, which typically influence utilities’ stock returns more than those of most other sectors. Utilities stocks have continued to climb despite 10-year US Treasury yields remaining above 4% and inflation staying above 3%.
We think the rally and the sector’s historically high valuations reflect a step up in the market’s earnings growth expectations. Utilities should benefit from secular trends such as clean energy growth, data center energy demand, manufacturing onshoring, and economywide electrification. Most utilities are planning for the most energy demand growth and capital investment over several generations. We expect earnings to grow at least 5% annually for most utilities through 2030.
Market’s Lofty Growth Expectations Have Inflated Many Utilities’ Valuations
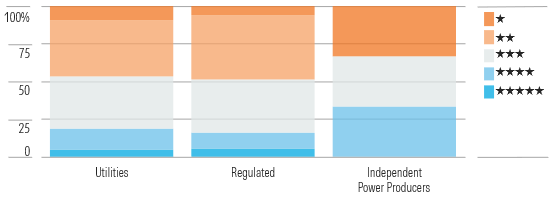
However, investors have become too enthusiastic. Utilities rarely have outperformed the market for this long. We consider the sector 7% overvalued as of late June. Despite the strong fundamentals and growth opportunities, we think investors should prepare for lower returns ahead.
Utilities’ Dividend Yields Rarely This Low Relative to Interest Rates
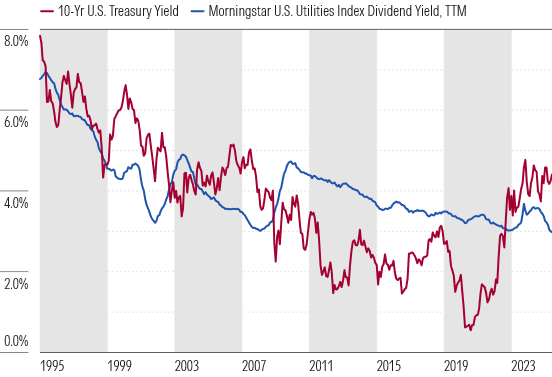
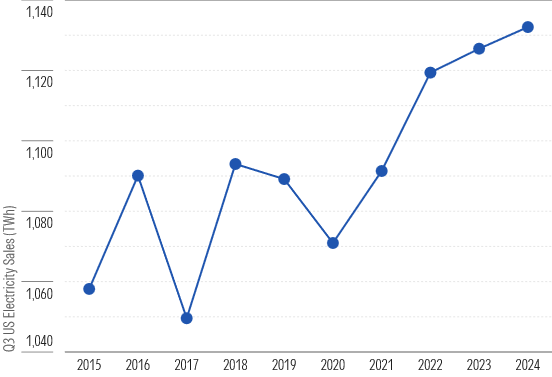
Long considered defensive stocks with high dividend yields, utilities have gained recent interest from investors, who are now more focused on earnings growth than dividends. Electricity demand this summer is set to hit a fourth consecutive record. Utilities are investing heavily to ensure they can meet growing demand with a cleaner, safer, and more reliable energy supply. If utilities can keep customer costs low and work with regulators, we expect they will be able to deliver the earnings growth that the market is anticipating.
US Electricity Demand Could Reach Record High This Summer
Top Utilities Sector Picks
Eversource Energy
- Fair Value Estimate: $73.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: None
- Morningstar Uncertainty Rating: Low
Eversource ES will miss out on most of the data center growth excitement but has plenty of investment opportunities in transmission and distribution to support at least 6% annual earnings growth, at least through 2028. Eversource has largely eliminated its offshore wind exposure and is expected to derive all its earnings from its rate-regulated utilities by 2025. We think Eversource can offset regulatory challenges in Connecticut by adding projects in Massachusetts, where regulation is more constructive. A turnaround in Connecticut offers earnings and valuation upside. Eversource’s balance sheet leverage should be back to normal range by the end of this year.
Duke Energy
- Fair Value Estimate: $117.00
- Morningstar Rating: ★★★
- Morningstar Economic Moat Rating: Narrow
- Morningstar Uncertainty Rating: Low
Duke DUK has a clear pathway to achieving management’s 5%-7% annual earnings growth target supported by the company’s regulated subsidiaries. Duke’s $83 billion capital investment plan for 2025-29 is focused on clean energy, grid infrastructure upgrades, and supporting load growth. We don’t think the market appreciates the upside to Duke’s capital plan and additional electricity demand growth from data centers. In North Carolina, Duke’s most important jurisdiction, regulation has improved significantly due to recently passed legislation.
Edison International
- Fair Value Estimate: $80.00
- Morningstar Rating: ★★★★★
- Morningstar Economic Moat Rating: Narrow
- Morningstar Uncertainty Rating: Medium
Edison’s EIX stock is down $30 per share, or $11.6 billion of market value, since the January fires. We think Edison will qualify for California’s AB 1054 Wildfire Fund, which should eliminate nearly all shareholder losses. We estimate an AB 1054 worst-case scenario is $4.4 billion of losses, or $8 per share after tax. Widespread electrification to meet California’s 2045 carbon-neutral target is a huge growth opportunity. Edison is set to invest more than $7 billion annually over the next four years, supporting an average annual earnings growth of 7%, which is at the high end of management’s 5%-7% target.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States