
New Enhancements for Morningstar’s Semiliquid Fund Medalist Ratings
Here’s what to know about the updated semiliquid fund rating methodology.
Morningstar is launching an enhanced methodology for Morningstar Medalist Rating for Semiliquid Funds on Wednesday, Oct. 16, to incorporate new proprietary fee data and expertise from over a year’s worth of semiliquid fund ratings. The two main enhancements include an improved price-scoring methodology and a minor adjustment to the final rating breakpoints, which are described in more detail below.
Improved Ratings Start With Better Data
The first change coincides with Morningstar’s launch of Semiliquid Cost Estimate data points, which provide a more consistent and comparable assessment of semiliquid fund fees than is possible using the expense information disclosed in a fund’s prospectus.
Semiliquid Adjusted Cost Estimates, specifically, will be used to build a distribution of semiliquid fund fees for scoring. This data takes the elements of a fund’s fee structure and removes discretionary assumptions built into the prospectus expense ratio and replaces them with standardized assumptions set by Morningstar and applied by Morningstar Category.
The goal of these assumptions isn’t to predict future performance or set capital markets assumptions. They are generalized and long-term-oriented, trading precision for focus on the fee structures and their comparability. For private equity funds, the gross return assumption is 10%, driven by capital gains. For the private debt-direct lending category, the assumption focuses on income, not capital gains, and requires a dynamic gross return that moves with interest rates, in this case, SOFR (a broad measure of overnight borrowing rates) + 5%. Allocation funds that combine equity and debt exposures assume a mix of capital gains and income. If a fund uses leverage, gross returns are scaled by the leverage amount and assume a borrowing cost of SOFR + 2%. These assumptions generally align with long-term borrowing rates and performance of each asset class.
Incentive fees are calculated using the final return assumption and are then combined with a fund’s management fee, acquired fund fees and expenses, servicing and distribution fees, and other fees, as reported in the prospectus, to arrive at the final cost estimate.
Standardized assumptions put funds’ cost estimates on equal footing, allowing for a more granular approach to fee scoring. The previous methodology broke semiliquid fund fees into thirds by asset class, with the cheapest third receiving a score boost and the most expensive third a score deduction. More precise cost estimates allowed us to move to a continuous fee score in the new methodology.
Continuous fee scoring improves on the previous methodology in two ways. First, a fund with 66th percentile fees was previously scored significantly higher than a fund with 67th percentile fees (and likewise for a fund with 33rd percentile fees versus one that fell in the 34th percentile). Second, that fund with a fee in the 67th percentile was scored the same as the most expensive semiliquid fund despite significantly higher fees for the latter.
Fixed-Income Semiliquid Funds on a Continuous Price Score Versus Terciles
Ranking fees doesn’t account for the magnitude of differences between each fund. The new methodology uses a modified z-score to solve this. The range of scores retained its negative skew because of semiliquid funds’ high fees relative to public market mutual funds and exchange-traded funds, moving from a range of negative 0.50 to 0.25 to a range of negative 0.75 to 0.50 (cheaper fees result in a higher score). The result of these changes better reflects where a fund’s fee falls compared with other semiliquid funds in the same asset class.
Fee Scoring Without Cost Estimates
Semiliquid Cost Estimates are only calculated for US semiliquid funds and exclude unlisted REITs and private funds. Non-US semiliquid funds will continue to use regional fee data points, namely Total Cost Ratio—Prospective in Australia and New Zealand and Representative Cost ex Transaction Fee in the rest of the world. However, the new continuous scoring system will still be applied using these data points.
Changes to Medalist Rating Breakpoints
Medalist Rating breakpoints are reduced by 0.25 in the new methodology. Process, People, and Parent Pillars are assigned a value for ratings from low (negative 2) to high (2). Those scores are then weighted (50% Process, 25% People, 25% Parent) before adding the price score to get the final medalist score. Previously, a score of 2 was required for a Gold rating, meaning each pillar must have received a High rating from an analyst along with a median or better fee score to receive Gold. The new breakpoint is 1.75, which allows a fund with a median fee score to have an Above Average pillar and still receive Gold. This nudges the semiliquid fund rating methodology closer to the Medalist Rating methodology for mutual funds and ETFs.
New Medalist Rating Breakpoints
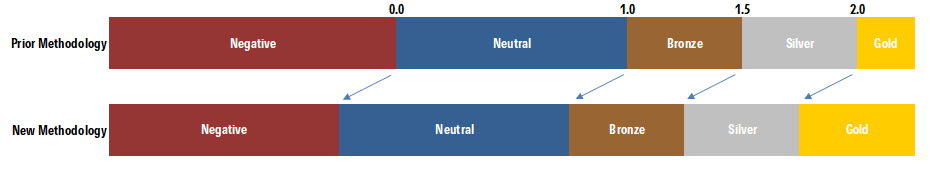
The median semiliquid fund’s fee score is now negative 0.125 instead of 0, so the deduction to rating breakpoints is effectively only 0.125. Higher fees and less transparency remain a barrier to long-term success, so Morningstar will continue to reserve Bronze, Silver, and Gold ratings for funds that Morningstar assesses as having sufficiently strong management teams, investment processes, and parent firms that can reliably carve out an after-fee edge over public market alternatives over the long run.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States